When mining becomes strategic: are critical minerals testing investor-state arbitration?


This article has been supplied.
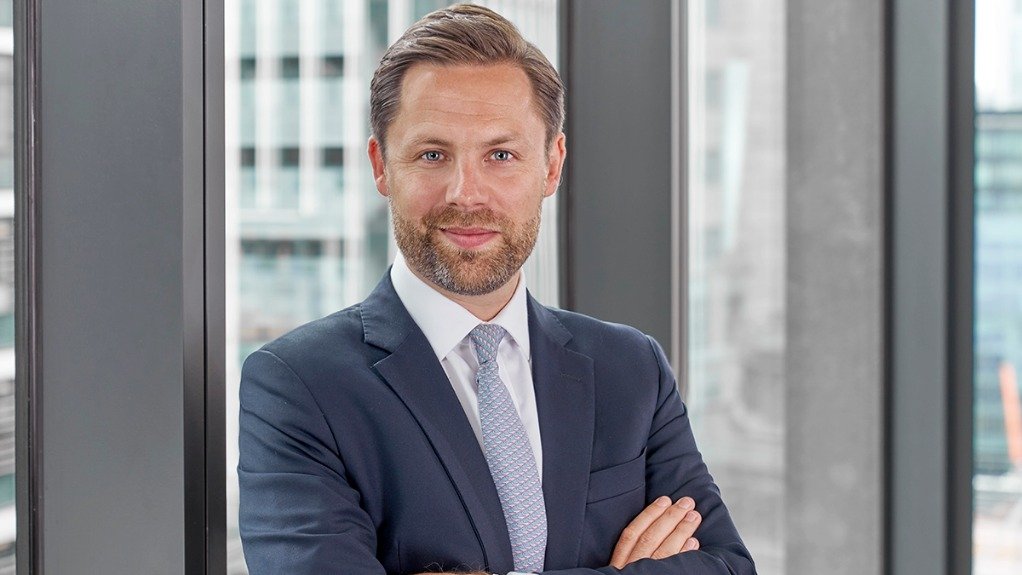
By: Daniel Wilmot - Partner at Stewarts specialising in international commercial and investor-state arbitration
As critical minerals become geopolitically strategic, resulting disputes become political. Investor-state (or investment treaty) arbitration is a common forum for such disputes. Daniel Wilmot, International Arbitration partner at Stewarts asks: Does this present a challenge for such arbitration? If so, how should it acknowledge such reality?
Across Africa, a “new wave” of mining disputes is emerging. A recent data-led analysis by Stewarts, a disputes-only law firm, identified 43 publicly reported mining-related investor-state arbitrations brought or contemplated against African states between 1 January 2020 and 24 June 2026.
The disputes analysed concerned bauxite, graphite, uranium, lithium, cobalt, copper, and gold. Many arose from measures affecting mining rights, including revoking or suspending licences, changing regulatory frameworks, refusing to extend or implement operating arrangements, and removing control over mining assets.
Although that analysis was subject to the methodology and limitations described, it nonetheless points to a trend. One resulting question may be whether such a trend is limited to a mere increase in case numbers, or whether it reflects a change in the environment in which mining disputes are arising. As states increasingly regard certain mineral resources as strategically important, what impact is that having on dispute resolution?
And if there is an impact, how should a three-person tribunal in closed-door arbitration proceedings address political considerations without allowing them to determine its decisions?
From private concessions to strategically important assets
Critical minerals are not a single, fixed category. What makes a mineral critical depends on a number of factors: availability, its application, the concentration and security of its supply and (as illustrated by the events in the Strait of Hormuz) the consequences of disruption.
Lithium, cobalt, nickel, and graphite are important to battery production. Rare earth elements have applications across advanced manufacturing and digital technology. Uranium, of course, remains significant to nuclear-energy supply. The result is that a mine producing these resources may no longer be regarded simply as a privately operated commercial asset. Such assets will increasingly form part of a state’s industrial strategy, energy policy, and geopolitical value and bargaining. As the International Energy Agency (IEA) put it in its Global Critical Minerals Outlook 2026 report, “critical minerals have rapidly moved to the heart of global discussions on energy and economic security”.[2]
Africa plays a central role in this evolution. The continent possesses substantial deposits required by an increasingly mineral-hungry world. Yet, it is said it captures only a limited share of their economic value: extracting and exporting raw minerals often produces far less domestic value than the processing, manufacturing, industries, and technologies they support.
It is understandable that African states should thus seek a greater participation in their mining sectors. This may take the form of increased royalties or state ownership, domestic-processing requirements, revised fiscal arrangements, export restrictions or, at its extreme, the forced reallocation of mining rights altogether.
This shift is often coined “resource nationalism”: linguistically accurate but a label that may obscure legitimate development questions. states must manage natural resources in their people’s interests and ensure their development produces meaningful economic benefit.
A legitimate political objective does not automatically validate the means of pursuing it, however. Mining rights will remain governed by contractual commitments, domestic legislation and regulation, and international treaties guaranteeing certain investor rights.
Here the tension arises. Investors should expect regulation to evolve over time, especially during long-term mining projects, but will still also expect the protections treaties seek to guarantee, ie, that state decisions be consistent, fair, equal, and transparent.
Disputes often arise where those expectations meet.
The ‘wave’ of such disputes on the continent
As the same IEA report notes, countries are introducing measures to protect and preserve their mineral interests. To point to a few examples, the Democratic Republic of Congo (DRC) has introduced a cobalt export quota. Zimbabwe and Mozambique have imposed trade restrictions on lithium and graphite, respectively. The IEA cites the DRC quota policy as a real example of global supply risk.[3]
This context perhaps explains the perceived increase (or wave) in mining-related disputes across the continent. The earlier Stewarts analysis identified, for example, five mining-related arbitrations involving Guinea, all brought in 2025 or 2026, following a five-year period in which no such case had been identified. Four cases were identified involving Niger, all brought in 2024 or 2025, while two cases concerning Burundi were brought in 2026. Further disputes involving Mali and the DRC arose at different points between 2020 and 2026.
Alongside the growth in numbers, the cases also revealed a degree of consistency in the measures giving rise to the claims. Those measures principally affected the ownership, control, or continued validity of mining rights. And that pattern appears to remain current. Of the 17 cases comprising the relevant part of the dataset, 13 were recorded as pending in early September 2026. One of the most recent, Falcon Energy Materials PLC v Republic of Guinea, was commenced on 16 March 2026 and registered by the International Centre for Settlement of Investment Disputes (ICSID) on 31 March 2026[4]. In that case, the claimant investor alleges that Guinea unlawfully revoked the exploitation licence for the Lola graphite project and seeks compensation under the 2011 United Arab Emirates-Guinea bilateral investment treaty.
These developments do not establish that all mining disputes are becoming political or that every state measure affecting a mining project reflects a coordinated strategy. The wider dataset reviewed by Stewarts includes conventional contractual, fiscal, and ownership disputes that cannot properly be attributed to “resource nationalism” in the sense described.
The dataset nevertheless indicates a potential structural shift in both how and why a growing number of disputes are arising in the mining and minerals space across Africa.
Public interest versus legal entitlement
If that is right, the political imperatives underlying the sources of some of these disputes are being assessed by tribunals constituted in the investment treaty arbitrations charged with resolving them. This means such tribunals will face defences justified by reference to domestic value creation, environmental protection, national security, supply chain resilience, local community stakeholder interests or, more generally, the need to correct a perceived unequal allocation of the economic benefits flowing from the use of such minerals.
Tribunals will be pressed to take these points seriously. And the due process nature of arbitration is such that tribunals may well be required positively to engage with them. So tribunals cannot ignore such considerations, especially where they are relevant to the applicable legal standards under treaties. But, equally, they cannot be treated as a substitute for legal analysis. The political (or econo-ethical) cart must not be put before the legal horse.
How might such public interest points be best understood in an arbitral context? Perhaps as part of the factual and regulatory context in which legal rights operate. It might inform the assessment of an investor’s legitimate expectations, the character and purpose of a state measure, whether treatment was arbitrary or discriminatory, and whether the measure bore a rational or proportionate relationship to its stated objective. It might also affect analyses of causation, contributory conduct, and damages. But, absent express treaty wording, care should be taken to avoid it becoming a free-standing basis on which legal rights are displaced.
The principles are perhaps clearer. The strategic importance of a mineral does not give a state an unrestricted licence to disregard contractual or treaty obligations. Equally, investment treaty protection does not guarantee that the legal and regulatory environment will remain unchanged throughout the decades-long life of a mining project. Although such principles are easy to state, it may well prove harder to apply them in practice in a dispute.
Transparent reasoning in awards therefore assumes particular importance. Tribunals should identify why wider context is legally relevant, the weight attached to it, and how legitimate regulation is distinguished from compensable wrongdoing. Each case turns on its merits, but such discipline should allow arbitration to recognise political and developmental realities without becoming political in itself.
It is not just the reasoning; it is who formulates it
If transparent reasoning gains greater importance in the context of such politically infused cases, so does the identity of those formulating it. This changing dispute landscape has implications for tribunal constitution, particularly because tribunals are partly party-appointed.
It is an oft-commented perception that some arbitrators in investment treaty arbitrations are known to be investor- or state-friendly. Critical-minerals cases should not require ‘political’ arbitrators, or those selected for presumed sympathy with state sovereignty or investor protection. They require tribunals able to distinguish political assertion from legally relevant context and understand the technical and economic evidence on which that distinction depends. Tribunal expertise is therefore likely to be a key consideration in its selection.
Depending on the dispute, relevant experience may therefore extend beyond investment treaties and commercial arbitration to include mining operations, concession structures, public administration, environmental regulation, sanctions and trade controls, community rights and the valuation of long-term or pre-production assets. No single arbitrator will likely possess expertise in every relevant area. The objective thus should be to build a tribunal with complementary skills and experience. Although this would require party collaboration that is unlikely to be available or feasible in practice, it is a laudable target to be borne in mind.
This might also engage a wider conception of diversity. Quite rightly, much of the debate in the arbitration community has been on diversity of gender and geography/nationality. But diversity of professional experience and perspective may be equally significant in these cases. While technical experts will always remain essential, they cannot cure every gap in a tribunal’s understanding. The tribunal needs to be alive to the wider context that this article describes.
A corresponding shift in risk assessment?
Being alive in this way doesn’t mean that a state’s acts should be carefully scrutinised alone. Plainly, investors must expect (and a tribunal will expect them to expect) project risk as part of their investment feasibility assessment and project lifecycle. The political and regulatory risks touched upon above might be said to be increasingly central to an investor’s overall risk assessment. That is not to say, of course, that awareness amounts to an acceptance of unlawful action.
Thus, while treaty structuring certainly remains important, investors may need to carefully map the entire framework of protection: including licence terms, mining legislation, investment codes alongside contractual commitments, stabilisation provisions, and applicable dispute-resolution mechanisms across the transactional suite of documents. Stewarts’ analysis bears this out: the disputes identified in that research arose not just under investment treaties, but also under contracts and domestic investment laws, including mining codes.
Plainly, investors should also examine whether their project aligns with the host state’s stated development objectives. Local processing, state participation, community benefit, environmental performance, and the pace of project development are now central to the long-term durability of the investment, not just peripheral questions of corporate responsibility.
Still, states obviously also have a careful role to play. They should properly assess potential dispute exposure while reforms are being designed, rather than waiting until a notice of dispute arrives. To give but a few examples: clear and contemporaneous reasons for decisions, consistent treatment of comparable projects, observance of contractual processes, and documented engagement with investors may be key in any subsequent arbitration.
So where does this leave investment treaty arbitration?
Critical minerals disputes are testing investor-state arbitration because the assets at their centre can no longer be understood solely as private investments. They may also be instruments of national development, energy security, and geopolitical strategy.
That must not require tribunals to depart from law in favour of politics (or, put more lightly, econo-ethical outcomes). It requires them to apply existing principles with a sophisticated understanding of the context in which competing rights and obligations operate.
The real test is not whether investment treaty arbitration can adapt to critical minerals disputes, but whether it can do so without compromising the neutrality and legal discipline on which its legitimacy depends. The current wave will be one test of how well it succeeds.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Research Reports
Latest Multimedia
Latest News
Showroom
We are responsible manufacturers of essential components. Manufacturing 80 million parts a week, we have over 1 billion parts in stock.
VISIT SHOWROOM
Press Office
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation