Turning recycling into ‘mine’ is spelt out in BCG's critical minerals study
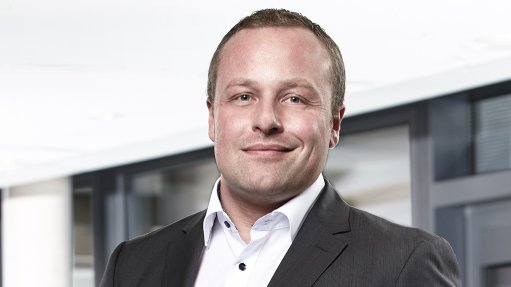
Tycho Möncks discussed BCG’s report, ‘Why Critical Mineral Shortages Are a CEO Issue’, which examines how companies can strengthen supply security and turn mineral shortages into business opportunities.


JOHANNESBURG (miningweekly.com) – Orchestrating product flows so that end-of-life material gets reused is the kind of circularity that turns a company’s installed base into a captive ‘mine’ that generates repeatable value over time.
This is spelt out by Boston Consulting Group (BCG) to lower risk in the field of critical minerals through a return incentive circularity measure – the offering of a discount on the new unit when the old one is handed back.
By implementing this closed loop, the ownership of the metal never really transfers.
Pointed out by BCG is that this is already standard practice at industrial-level catalysis when platinum group metals (PGMs) catalysts are essentially leased and the PGMs are re-refined for the next charge rather than being sold into the market.
This circularity step is just one of five steps that BCG lists in its latest report on how to overcome critical mineral shortages in today’s transitioning world and this is the sequence in which the five steps are listed:
- see risks across the entire value chain;
- spread the risk by diversifying suppliers;
- design out the risk;
- collect the risk through a recycling process; and
- secure the risk through greater access and control.
The compilers of the BCG report – Tycho Möncks, Karthik Valluru, Mikhail Nikomarov, Anna Temple, Thomas Vogt, Peter Clearkin, Aparna Bharadwaj, and Timm Lux – report that CEOs at industrial companies are well aware of potential shortages in critical minerals, and many think they have a plan in place to mitigate those risks. But it is consistently found that companies are continuing to underestimate their true vulnerability.
Most industrial companies track their exposure to critical minerals using high-level metrics such as spending, information from Tier 1 suppliers, or country-of-origin data.
However, true exposure is larger than those metrics suggest. This is because mineral risk is often deep inside supply chains, inside the components that companies buy, and inside the tools and processes used to make those components. Concentration risks require looking at processing and ownership, not just mineral production at the mine.
A more comprehensive approach can give an accurate view of the supply chain vulnerabilities and from that baseline companies can take a range of steps to reduce their exposure.
Critically, this approach also helps companies to access the pools of public capital that many countries have allocated.
In 2025, public finance commitments to critical minerals in advanced economies reached around $65-billion, more than four times the 2023 level, and most of that money is not yet spent. When companies have a clear sense of their financial exposure, they can build a case to access these funds.
In that way, industrial companies can stop treating critical minerals as a cost item and start treating them as a source of strategic advantage.
BLIND SPOTS
Companies often start their risk assessment by looking at their bill of materials, which leads them to worry about materials that are large in tonnage and procurement dollars such as copper and lithium.
But the more dangerous exposures are often in what BCG describes as ‘mosquito’ minerals. These are minerals that are so small by traded value that they never reach the risk register, yet are so essential that entire high-value chains stop without them.
Given as an example are rare earth elements (REEs), which comprise 40% of the cost of a magnet, but less than 1% of the total value of an electric vehicle that requires the magnet. That is too low to appear in any cost review that would flag it as a risk, yet a shortage of these elements can stop a production line.
Similarly, a jet uses about 20 kg of REEs, which are worth less in total than the paint that coats the plane, yet the aircraft does not fly without them.
While REEs have been receiving a lot of attention lately, the list of ‘mosquito minerals’ is considerably longer, with cited examples including gallium, germanium and arsenic.
Gallium’s entire global market is worth less than $350-million a year and its annual production of 900 t makes it negligible in comparison to most other commodities. Yet an estimated $3.5-trillion worth of final product depends on gallium, including high-speed logic and power chips and satellite communications components.
Germanium’s global sales total a comparatively low $260-million, but it is an essential component of electronics and fibre optics.
In ultra-high-purity form, arsenic is needed for gallium-arsenide semiconductors in telecom infrastructure, along with AI data centre optics and radar systems. The upstream market is roughly $50-million worldwide, and producing semiconductor arsenic at a purity level 99.999995% requires considerable process know-how.
Blind spot two is companies looking at critical minerals in the products and components they buy from their direct Tier 1 suppliers. Yet a company that buys almost no critical minerals directly can still be acutely exposed because minerals arrive embedded in components. A motor, magnet, power module, laser, or sensor carries upstream mineral content, leading to dependencies that may not appear on a raw-materials line.
Blind spot three is focusing on mineral production rather than processing and ownership.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Research Reports
Projects
Latest Multimedia
Latest News
Showroom
Rentech provides renewable energy products and services to the local and selected African markets. Supplying inverters, lithium and lead-acid...
VISIT SHOWROOM
Axiom Hydraulics is a trusted leader in South Africa’s hydraulic industry, delivering world-class components, systems, and engineering expertise...
VISIT SHOWROOM
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation