Afrimat’s revenue falls, but group cuts debt, grows aggregates business
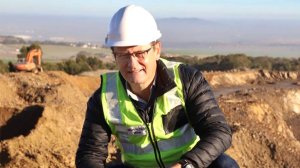


Multicommodity, midtier mining and materials company Afrimat faced its most challenging trading conditions since it listed in 2006, during the six months to August 31, with revenue having decreased by 4.3% year-on-year to R5.1-billion, mainly owing to lower revenue in the iron-ore and cement businesses, but partly offset by growth in the aggregates business and higher anthracite export volumes, group CEO Andries van Heerden says.
He points out that an “excellent” performance from the aggregates business was hampered by a decline in the profitability of the iron-ore business and continued operational challenges in cement.
Revenue generated by the aggregates and fly-ash businesses increased by 5.3% to R2-billion, while operating profit increased by 76.8% to R567.8-million, at an operating profit margin of 27.8%.
The cement business remained loss-making, with an operating loss of R146.1-million.
Construction materials revenue increased by 0.2% to R2.8-billion, while the unit’s operating profit more than doubled to R421.7-million from R194.1-million in the comparable six-month period in 2025.
Revenue from the group’s iron-ore and manganese mines decreased by 7.9% to R1.2-billion, as higher export volumes were largely offset by lower domestic volumes. Operating profit decreased to R11.3-million from R403.5-million, primarily owing to lower domestic sales volumes, weaker realised export prices and higher mining costs with the Demaneng mine reaching the end of its life.
“Cash generated from operations increased, supported by successful working capital initiatives. Net debt reduced and the net debt:equity ratio improved, reflecting management’s continued attention to cash preservation during this period of operational pressure.
“Management remained focused on optimising the portfolio and protecting the balance sheet. Loss-making and noncore operations were closed, disposed of or restructured. The resulting portfolio is more focused, and the benefits are visible in the aggregates business’ improved underlying margins, ”Afrimat states.
Operating profit, which includes a R95.5-million one-off profit on the disposal of divested operations, decreased by 32.8% to R255.2-million.
The overall decline was driven primarily by the bulk commodities segment, where operating profit decreased from R445.1-million to R8.6-million, and by the wider operating loss in the cement business.
These headwinds were partially offset by a strong performance in aggregates and a 30.6% reduction in centralised shared services costs to R194-million, largely owing to eliminating legacy information system costs.
On the positive side, and in line with actions taken by management, cash generated from operations increased by 21.1% to R433.1-million.
“The improvement was primarily driven by disciplined working capital management,” Van Heerden explains.
Earnings a share decreased to 2.6c from 102.7c in the prior comparable period, and the group reported a headline loss a share of 58c, compared with headline earnings a share of 101.9c.
The larger decline in headline earnings reflects the exclusion of the profit on the disposal of businesses, including divested operations, as well as the disposal of noncore assets.
Given the period’s results and the group’s continued focus on reducing debt and preserving cash, the board resolved not to declare an interim dividend for the six months under review.
Meanwhile, proceeds of R158-million from the disposal of businesses supported the repayment of borrowings. The net debt:equity ratio improved to 46% from 50.2% in February. All bank covenants remain within the limits set by the lenders.
OUTLOOK
The aggregates business is expected to maintain its improved performance, supported by a more focused portfolio, the benefits of completed capital projects and continued demand from rail maintenance and infrastructure work.
Further, with Kiln 3 back in operation from September 1, the cement business is expected to benefit from improved clinker availability. Management remains focused on plant reliability and throughput, and demand for low-carbon, high-quality cement remains strong. The investigation into strategic alternatives continues.
Iron-ore export volumes, meanwhile, recovered well towards the end of the period, but realised prices remain under pressure from high shipping costs and a stronger rand.
The Doornfontein resource will replace the mined-out Demaneng mine, with first iron-ore anticipated in the last quarter of the 2027 financial year.
Domestic iron-ore demand is expected to stabilise at 90 000 t to 100 000 t a month.
Nkomati’s lower cost base leaves it well placed to benefit from higher volumes as the domestic market improves and more smelters come online, supported by the group’s export strategy.
The industrial minerals segment expects to benefit from the reopening of the ferrochrome smelters, as well as import protection, which Afrimat says the government seems to be moving towards.
Afrimat will continue to prioritise cash generation, debt reduction and operational reliability.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Research Reports
Projects
Latest Multimedia
Showroom
For over 30 years, Werner South Africa Pumps & Equipment (PTY) LTD has been designing, manufacturing, supplying and maintaining specialist...
VISIT SHOWROOM
We are responsible manufacturers of essential components. Manufacturing 80 million parts a week, we have over 1 billion parts in stock.
VISIT SHOWROOM
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation