Renewable fixed-tariff PPA no longer only option – company
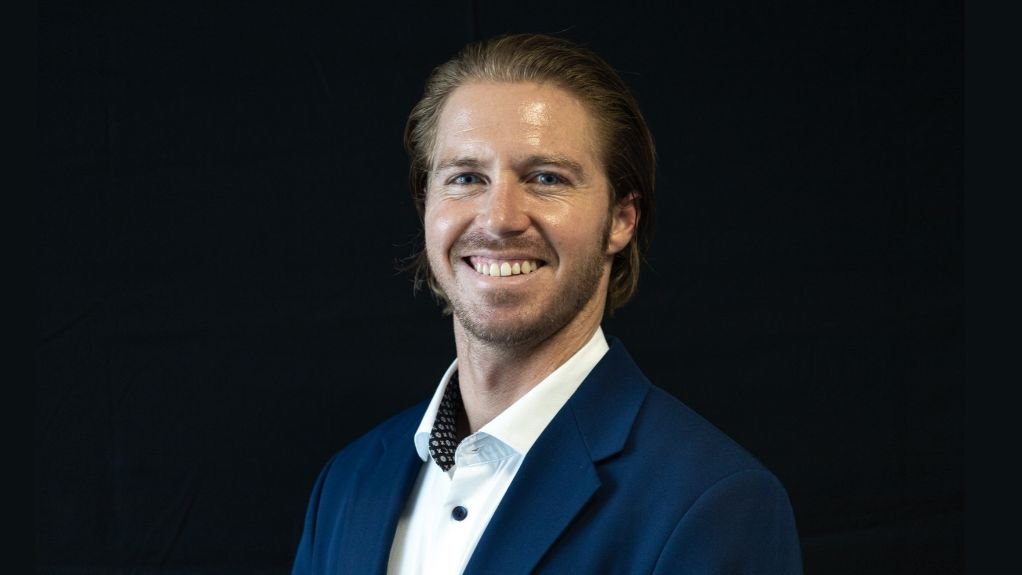
DOMINIC GONCALVES Developers and independent power producers are beginning to consider not only who will buy electricity, but how output can be divided, shaped, firmed, traded and reallocated over its operating life
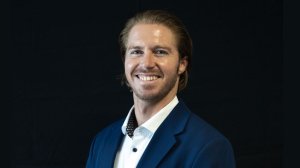


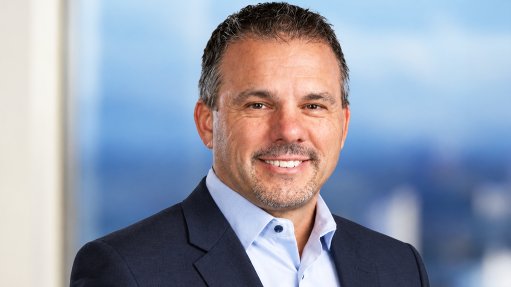
The dominance of the long-term, fixed-tariff power purchase agreement (PPA) as the sole bankable contract for renewable energy in Southern Africa is ending, says financial advisory company Cresco Project Finance energy strategy advisory partner Dominic Goncalves.
He notes that, for 15 years, the PPA has been the central contract underpinning independent power investment in the region, often supported by sovereign guarantees or credit enhancement, creating predictable cash flows, but concentrating risk in a single buyer.
That model is now being challenged.
“Corporate procurement, open access, wheeling, regional Southern African Power Pool trading, South Africa’s planned wholesale market and the deployment of battery storage are creating more routes to market, beyond a single buyer,” he explains.
Moreover, developers and independent power producers (IPPs) are beginning to consider not only who will buy electricity but how output can be divided, shaped, firmed, traded and reallocated over a project’s operating life.
The next generation of projects may have several revenue components, rather than one PPA, including, for example, a medium- or long-term corporate offtake agreement combined with sales through a trader, short-term market exposure, a merchant tail and storage-related revenues.
“A price floor or contract-for-difference structure could protect downside risk while preserving some market upside. A solar project paired with battery storage could sell a shaped evening product rather than undifferentiated daytime energy,” Goncalves says.
He notes that pooling buyers, diversifying revenue and introducing credible intermediaries can reduce concentration risk, particularly in markets where utility creditworthiness has constrained investment, citing Zambia’s emerging merchant and aggregation models as an example.
“A trader can aggregate multiple renewable-energy generators and combine solar, wind, battery, hydropower and market purchases, and supply a customer with a much more predictable product than any individual plant could.”
He adds that the trader can also manage forecasting, nominations, balancing, replacement power and short-term market exposure.
For industrial customers, such as mines, data centres and manufacturers, this optionality is increasingly important.
Industrial users generally do not want to manage the hourly mismatch between an individual solar project’s output and their own consumption. Offtakers increasingly demand competitively priced electricity with an agreed level of firmness, flexibility and security.
Goncalves adds that competition is no longer characterised by which IPP or developer can construct the cheapest solar plant, but which entity can assemble the most efficient portfolio and manage its risks.
Designing Around the Product
Goncalves says the South African electricity market is progressing from procuring a technology to procuring a product.
“Historically, in the 2010s for example, renewable-energy projects were developed in a relatively linear way: identify a strong solar or wind resource, secure land and grid access, and then seek a long-term PPA for the plant’s output. That sequence has begun to reverse.”
He points out that developers now scope out the product that customers require and work backwards, often incorporating multiple generation assets and contractual instruments to address load profile, risk and need for firmness.
Consequently, the best renewable resource is not always the best commercial project. The lowest cost per megawatt-hour is not always the most attractive solution, as time of use and delivery are increasingly more important.
“The strategic shift is moving from maximising bulk and cheap renewable-energy megawatt-hours to optimising the value of when, where and how reliably those megawatt-hours are delivered.”
Goncalves stresses that projects will not become “fully merchant”, as PPAs and government procurement rounds will continue, primarily because banks will still fund projects to generate predictable cash flow. However, he suggests that such predictability may come from a portfolio of contracts and hedges rather than a ‘take-or-pay’ agreement.
Future bankability will depend on evaluating capture prices, basis and shape risk, merchant tails, imbalance exposure, congestion, counterparty substitution and hedging effectiveness, while documentation will need to accommodate multiple contracts and revenue priorities.
For lawyers, future agreements will require “more sophisticated” provisions for dispatch, nominations, balancing, replacement power, market suspension, change in law, curtailment and credit cover, he adds.
“We are supporting some of our clients to develop battery energy storage systems and portfolio-backed products. Firming services and shaped, baseload and peak products are likely the first developed products to reach the market in the near term,” Goncalves says.
He adds that PPAs remain an important risk allocation instrument but may become one layer within a broader revenue stack, adding that future PPAs should be product-focused and define a particular delivery or risk-management outcomes.
“That could be a firm evening block, a shaped baseload profile, a minimum renewable-energy matching level, capped imbalance exposure or an agreed level of availability at a specified delivery point. The product should be designed around what the customer needs, rather than simply around what one generating plant happens to produce,” he concludes.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Projects
Latest Multimedia
Latest News
Showroom
SABAT Batteries is a renowned brand in the battery industry, manufacturing a wide range of batteries at its state-of-the-art production facility in...
VISIT SHOWROOM
AxFlow AQS Liquid Transfer (Pty) Ltd is an Importer and Distributor of Pumps in Southern Africa
VISIT SHOWROOM
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation