Opinion: Africa's biggest opportunity is not its minerals but the leverage they create
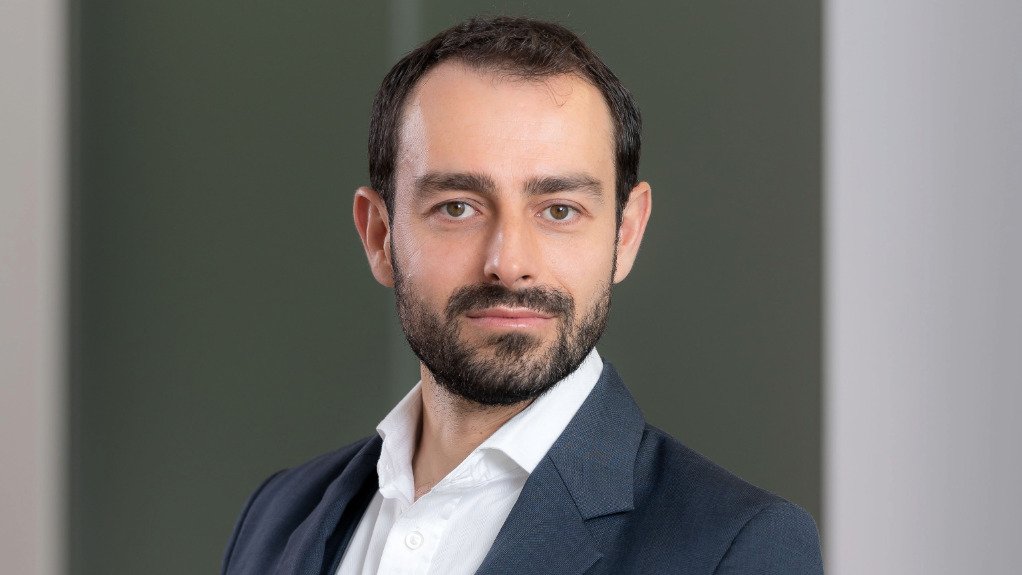


In this opinion article, Mikhail Nikomarov, a partner and associate director at BCG Johannesburg, argues that African countries do not need to capture every stage of every value chain to benefit from the opportunity that the global competition for critical minerals has created.
For years, discussions about Africa's resource wealth have revolved around a single question: how can the continent capture more value from what it extracts? It remains an important question, but a rapidly changing geopolitical landscape is forcing governments and investors to think differently about the role minerals now play in the global economy.
Over the past decade, minerals have become central to industrial policy, energy security and economic competitiveness. Global markets are not simply looking for access to raw materials; they are looking for access to very specific minerals that have become essential to future industries. In doing so, they have exposed an uncomfortable reality: a tonne of copper, a tonne of lithium and a kilogram of gallium may all fall under the broad critical minerals umbrella, but they operate in entirely different markets with different supply dynamics, competitive landscapes and sources of strategic leverage.
Some minerals sit within deep, globally traded markets where supply can be sourced from multiple regions whilst others operate in relatively small and opaque ecosystems where a disruption in one country can have consequences for entire industries. The strategic importance of a mineral is often determined less by how much of it exists and more by how difficult it is to replace.
Gallium rarely dominates headlines in the way lithium or cobalt does, yet it plays an essential role in semiconductors, telecommunications equipment and defence technologies. It’s not even mined on its own but produced as a byproduct of bauxite or zinc refining. Because supply is concentrated, decisions by a handful of producers (or one government) can have outsized effects across global industries.
Africa's opportunity may lie as much in these overlooked minerals and by-products as in the headline commodities that dominate global discussions, particularly where associated minerals remain under-commercialised.
Not every mineral creates the same economic opportunity or negotiating position, yet resource negotiations have traditionally focused on extraction rights, royalties and tax revenues. While those considerations still matter, they are only one part of the equation. Countries that understand where genuine dependence exists will be better positioned to negotiate for infrastructure, skills, technology and industrial development alongside investment.
The strategic environment has shifted markedly. The United States is seeking to strengthen access to critical minerals as it reduces reliance on concentrated supply chains. Europe is pursuing similar objectives, China remains dominant across much of the processing ecosystem, and India's industrial expansion is creating another significant source of demand. The result is a far more competitive market for African resources than existed a decade ago, with multiple economic powers seeking access to minerals they increasingly view as strategically important.
Competition for access changes the balance of a negotiation, creating space for governments to secure value beyond royalties and taxes. Infrastructure, skills, technology transfer and processing capability are often more important over the long term than the financial terms of an individual project.
Stronger bargaining power on its own does not create industries or jobs. Yet debates about beneficiation often become unnecessarily binary, framing the issue as a choice between exporting raw materials and capturing an entire value chain domestically.
Beneficiation debates often assume countries must either export raw materials or capture an entire value chain domestically. Few countries possess competitive advantages across every stage of production and pursuing that ambition can result in years of policy debate without meaningful economic progress.
The challenge is deciding where deeper participation genuinely creates value. In some sectors, that means processing. In others, it means component manufacturing or enabling industries. The answer differs by country, commodity and market opportunity.
Zambia's copper industry highlights the distinction between ambition and competitiveness. Manufacturing lithium-ion battery cells at scale may not be realistic in the near term, but expanding into electrical cables, wiring, equipment and selected battery components builds on capabilities that already exist. Recent investments in battery assembly and regional copper-cobalt processing initiatives show how countries can move further downstream without needing to own the entire value chain.
The experience of Africa's automotive sector offers a useful lesson. Countries like South Africa, Morocco and Egypt have not built competitive industries by attempting to replicate every stage of the global automotive value chain. They have focused on specific advantages, developed supporting ecosystems and connected production to demand.
Resource endowment alone is unlikely to determine which countries benefit most from growing demand for critical minerals. Greater returns will come from linking resource development to investment, new industries, market access and long-term demand.
That remains easier said than done as resource extraction, while formally managed through government departments, requires coordination from others on topics such as industrial policy, energy, water or logistics infrastructure and taxation. Meanwhile competitors are increasingly coordinating supply- and demand-side interventions as part of a single strategic agenda, making it easier to build industries around resources rather than simply extracting them.
For decades, success has largely been measured through tonnes exported and revenues generated. Those measures tell part of the story, but so do the capabilities created along the way. Africa does not need to capture every stage of every value chain to benefit from this moment. In many cases, securing additional processing capability, specialised skills, technology transfer or industrial capacity would represent meaningful progress.
The greater risk is spending so much time pursuing the perfect outcome that opportunities pass by. Global competition for critical minerals has created a window that Africa has not enjoyed before. The countries that benefit most are unlikely to be those pursuing perfect solutions. They will be those that move quickly, build on existing advantages and use today's bargaining power to secure capabilities that remain valuable long after the resource has been exhausted.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Projects
Latest Multimedia
Latest News
Showroom
Electrifying the world in a safe, smart, and sustainable way, ABB Electrification is a global technology leader in electrical distribution and...
VISIT SHOWROOM
SafeQuip is a leading distributor and manufacturer of fire safety solutions, offering a comprehensive range of products designed to meet all...
VISIT SHOWROOM
Press Office
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation