Miners bound to megadeal playbook in pursuit of global scale


LONDON – Mining companies are set on building scale through M&A and partnerships to tackle financial and geopolitical hurdles, despite several thwarted megadeals over the past year.
Gold Fields, whose $27.1-billion offer to forge the world's second-largest gold producer was rejected by Northern Star on Monday, is the latest to go into battle.
Gold Fields is employing the same reasoning as copper miners: diversification, synergies and financial strength.
"These big miners tend to fund project development through their balance sheet using debt rather than capital raising, so they need to be bigger to have more cashflow to manage that debt," said analyst Glyn Lawcock at Barrenjoey.
Although BHP failed in its bids for Anglo American and Rio Tinto abandoned its Glencore approach, investors and people familiar with boardroom discussions say boards remain convinced that bigger is better to obtain financing for multi-billion-dollar mines.
Mining companies also face huge political pressure to secure copper and other critical minerals that are at the forefront of energy, economic and national security agendas.
New copper mines can cost $10-billion to $20-billion to develop and take a decade or more to build, raising questions about whether companies have the financial heft to compete in a market where quality deposits are increasingly scarce.
"Increasingly, this isn't simply about the size of the orebody. It's about who has the balance sheet and capabilities to fund, permit, build and staff a long-duration project," said Richard Sellschop, McKinsey senior partner.
GROWTH AND DISCIPLINE
Shareholders who endured writedowns from the industry's last M&A spree are demanding that any growth come with strict capital discipline, creating a fundamental challenge for boards.
"The scale argument is a very valid one," said George Cheveley, portfolio manager at NinetyOne, adding that as mining becomes increasingly political over critical minerals, mid-sized miners lack the scale to navigate government intervention.
But scale is not universally beneficial, Sellschop said. It creates advantages in capital-intensive assets such as smelting and refining, but can become a disadvantage in niche markets.
Unlike the dealmaking binge of the 2000s, boards now insist growth must coexist with, not replace, shareholder returns.
METAL POLITICS
Mining has become more risky as governments seek control over critical minerals, making size more valuable as protection against resource nationalism, investors and analysts say.
Countries from Indonesia to Chile have moved to increase state control over mining assets, while the US and EU have introduced trade restrictions aimed at reshoring supply chains.
BHP's failed $49-billion approach for Anglo American has reinforced a preference for internal growth and joint ventures over transformational M&A. At least for now.
The company's partnership with Lundin Mining represents a strategy of spreading risk across multiple developments rather than betting on a single large acquisition.
Investors say they are willing to back growth, but only if it meets higher hurdles than in the past. Some distinguish between organic growth and joint ventures versus large acquisitions that can destroy value if integration fails.
The mining industry's last growth phase ended badly.
Companies including BHP, Rio Tinto and Anglo American spent heavily on acquisitions between 2005 and 2012, only to write down-billions when commodity prices collapsed.
That led to a decade focused on cost-cutting, asset sales and returning cash. But capital required to develop new deposits has soared while supplies have dwindled, forcing boards to confront whether their companies are large enough to compete.
Rio Tinto's tie-up with Glencore remains a possibility, investors say, even though CEO Simon Trott has pointed away from such M&A, saying it "should be looking to partner and bolt-on".
Glencore, meanwhile, remains committed to building scale.
MKI Global Partners said in a note that the copper rationale remains and Glencore's recent moves could ease structural issues relating to dealmaking, with the Swiss-based miner pursuing an Australian listing to broaden its shareholder base there.
"While none of this is explicitly linked to Rio, the combination of a stronger standalone business, greater Australian relevance ... means the backdrop to any renewed discussions may look somewhat different today," MKI said.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Projects
Latest Multimedia

Latest News
Showroom
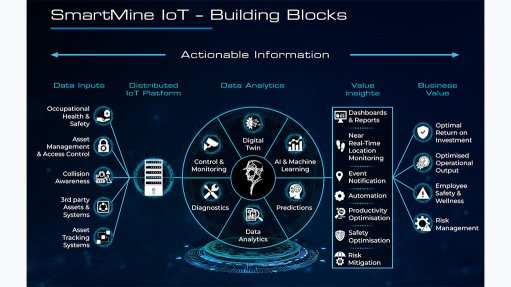
SmartMine IoT has been developed with the mining industry in mind, to provides our customers with powerful business intelligence and data modelling...
VISIT SHOWROOM
At Airshrink - CiP, we surpass customer expectations with innovative MV and LV cable accessories, including heat shrink joints, terminations,...
VISIT SHOWROOM
Press Office
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation