Industrial metals post mixed third-quarter performance, downside risks persist
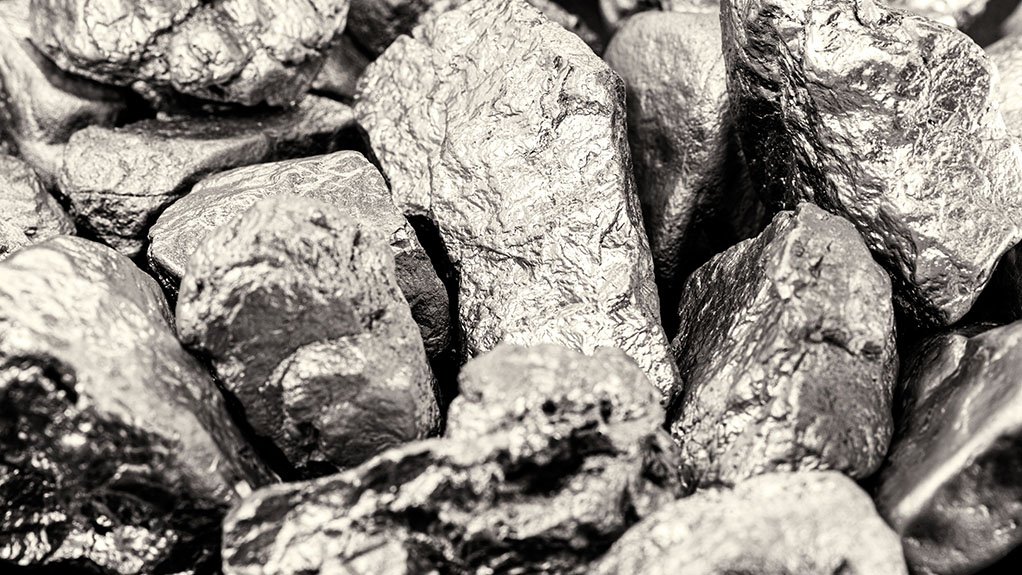
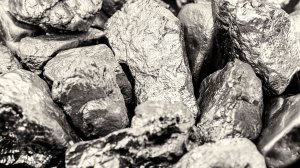
Tin prices were a standout, rising 33.5% in the year-to-date to $54 125/t as of October 7
Photo by Adobe Stock


Industrial metals have come under broad pressure in recent weeks, falling 3.3% month-on-month as of October 7, as expectations of a more hawkish US Federal Reserve weighed on sentiment across the complex.
Individual supply and demand fundamentals, however, continue to dictate relative performance, with some metals proving more resilient than others despite mounting macroeconomic headwinds, BMI, a unit of Fitch Solutions, points out in its ‘Outlook for Metal Prices’ report.
For the remainder of the year, expectations of further monetary tightening are likely to remain a key downside risk for industrial metals prices, the report indicates.
With the US-Iran conflict now expected to extend into 2027, inflationary pressures are likely to stay elevated for longer, reinforcing expectations of a higher-for-longer interest rate environment, according to BMI.
The unit notes that this is likely to weigh on industrial metals demand expectations and limit upside across the complex.
Despite mounting macroeconomic headwinds, performance across the industrial metals complex has been highly divergent.
Critical metals exposed to strong long-term structural demand trends stemming from the AI investment boom and the energy transition, continue to rank among the strongest year-to-date performers, the report points out.
It identifies tin as the standout, rising 33.5% in the year-to-date to $54 125/t as of October 7, as continued investment in AI infrastructure has strengthened expectations for a significant expansion in global data centre capacity.
As a key input in electronic solder used across servers and other data centre equipment, tin is well placed to benefit from this build-out, the report highlights.
BMI expects prices to stay elevated despite a modest 1.8% month-on-month decline, as tighter monetary expectations continue to weigh on the broader industrial metals complex.
Rare earths and lithium also posted strong gains, rising 27% to $110 268/t and 15% to $19 588/t respectively in the year-to-date.
Rare earth prices have been supported by ongoing concerns over Chinese export restrictions, reflecting the critical role of rare earth permanent magnets in both digitalisation and the energy transition, the report explains.
Meanwhile, lithium prices have rebounded as growing supply concerns have compounded demand-side tailwinds, strengthening expectations of a tighter market over the coming years.
Not all metals have proved as resilient, however, with concerns over the near-term demand outlook and easing supply risks taking centre stage, the report cautions.
Aluminium recorded one of the sharpest declines, falling 6.1% month-on-month to $3 111/t and narrowing its year-to-date gain to just 3.9%.
Prices are now hovering close to the lower end of BMI's expected $3 100/t to $3 400/t trading range, as concerns over potential supply disruptions in the Middle East have eased, while rising Chinese exports and additional capacity in Indonesia and India expected to come online in 2027 point to a looser supply outlook.
BMI maintains this range for now and continues to forecast a yearly average of $3 280/t this year, with a persistent market deficit expected to provide a floor under prices despite a more challenging near-term outlook.
Nickel also weakened notably, declining 5.5% month-on-month to $15 800/t as signs of a more accommodative policy approach towards Indonesia’s domestic nickel industry have eased supply concerns.
For the rest of the year, BMI expects prices to stay under pressure as government seems to have changed its tone, but to not deviate too far from current levels, as the government continues to focus on keeping a floor under prices.
Copper proved more resilient relative to other base metals, slipping just 0.8% month-on-month while still up 16% year-to-date.
Prices continue to hover near record highs, easing marginally to $14 400/t on October 7 after reaching a fresh all-time high of $14 875/t on September 10.
Strength in the market has been driven largely by trade-related inventory shifts.
For the remainder of the year, BMI expects copper prices to remain elevated given ongoing supply concerns and tight inventories outside the US.
However, it does not believe current price levels are fully supported by underlying market fundamentals, with much of the recent strength reflecting tariff-driven inventory shifts and trade dislocations rather than a sustained improvement in physical demand.
Ferrous metals presented a more mixed picture and are likely to continue lagging the broader industrial metals complex through the year-end, the report posits.
Iron-ore (62% iron content) at Qingdao port was the clear underperformer, falling 14% in the year-to-date and 6.1% month-on-month to $90/t as of October 7, amid persistent concerns over China’s steel demand outlook, particularly in the property sector.
Concurrently, expectations of growing seaborne supply, including additional volumes from major producers and the ongoing ramp-up of Guinea's Simandou project, have reinforced expectations of a more well-supplied market, placing further downward pressure on prices.
In Mainland China, the world’s largest steel producer and consumer, steel prices have been relatively resilient through much of the year despite mounting demand-side pressures.
While higher steelmaking costs and trade-related supply constraints will continue to provide a floor under global steel prices in the fourth quarter, these forces are no longer driving clear upside, the report points out.
It says that instead, prices are likely to trade broadly range-bound, with risks tilted to the downside as macroeconomic headwinds, elevated geopolitical tensions and China’s subdued property sector weigh on the consumption outlook.
Oil markets continue to send mixed signals, with Brent retesting support at around $100/bl this week, before recovering to over $104/bl on October 8.
Despite the ongoing US-Iran conflict, Gulf supply has continued to rise, and Asian crude imports have also been rising but are lagging the recovery in exports.
As a result, the market deficit has narrowed considerably.
Brent has now retreated from its $110/bl September highs and market positioning has skewed more bearish.
That said, given all of the above, oil remains relatively well supported, while a steeply backward dated futures curve and healthy premiums of physical over paper barrels point to continuing tightness in the underlying market for crude, the report notes.
With BMI’s Country Risk team now expecting a US-Iran deal to be delayed until the first quarter of 2027 (from quarter three this year previously) the unit has raised its Brent futures forecast to $93/bl, from $83/bl, and the 2027 forecast to $81/bl, from $71/bl.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Research Reports
Latest Multimedia
Latest News
Showroom
Sika South Africa is a trusted partner for the nation’s infrastructure, commercial, residential, and industrial sectors.
VISIT SHOWROOM
Rentech provides renewable energy products and services to the local and selected African markets. Supplying inverters, lithium and lead-acid...
VISIT SHOWROOM
Press Office
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation