China turns on the export taps as LME zinc squeeze grinds on
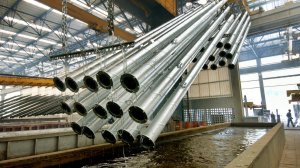


LONDON - China has historically been a significant net importer of refined zinc, but that looks set to change this year.
Exports surged to 40 668 tons in August, the second-highest monthly tally in almost 20 years, according to the World Bureau of Metal Statistics, which collects data from official customs figures.
With imports slowing to a trickle, the country was already a net exporter to the tune of 4 388 tons in the first eight months of the year.
A rolling squeeze on the London Metal Exchange (LME) zinc contract has opened up an arbitrage window with Chinese domestic prices through which an accelerating flow of metal is moving.
The tightness on the London market has abated somewhat since late August, when the cash premium over three-month delivery exploded to $215 per ton.
But the benchmark spread is still in backwardation and zinc is still being delivered almost daily to LME warehouses in Hong Kong, suggesting China's August surge extended into September.
The tectonic shift in China's zinc trade mirrors a growing divergence in global market dynamics.
While China's zinc production is growing, Western smelters are struggling to compete. The latest addition to the at-risk list is the Budel plant in the Netherlands.
SHIFTING TO NET EXPORTER
Chinese deliveries of zinc bailed out LME shorts late last year, and they're doing the same now.
LME warehouses in Hong Kong have received 35 000 tons since the middle of August. The city has been the primary point of arrival, followed by Singapore (21 250 tons) and the Taiwanese port of Kaohsiung (16 725 tons).
These three locations accounted for 80% of China's outbound shipments in August.
LME-registered inventory has risen from a mid-August low of 88 000 tons to 126 975 tons, the highest since June last year.
China's delivery surge has capped zinc's rally. The three-month price has slipped from a four-year high of $4 065 per ton in early September to $3 715 per ton.
It's also helped assuage the tightness in the market, but cash metal continues to command a hefty $60-per-ton premium over metal for three-month delivery.
The incentive for more Chinese exports is still there, and the country is on course to become a net annual exporter for the first time since 2022, when the Western supply chain was hit by a string of smelter disruptions.
It's not as if the Chinese market is short of zinc.
Muted construction activity has dampened demand for galvanised steel, and Shanghai zinc inventory is still higher than that of the London market at 143 527 tons.
EAST-WEST DIVIDE
While China has too much zinc, the West is facing a growing shortage, reflected in the persistent tightness on the LME.
Western refined zinc output contracted by 3.4% year-on-year in the first half of 2026, according to the International Lead and Zinc Study Group.
It may slide further depending on the outcome of a strategic review of the Budel smelter by operator Nyrstar, owned by commodities group Trafigura.
Budel "is losing money every year, and the conditions for next year look particularly difficult," was the stark warning from Nyrstar CEO Guido Janssen.
Like many of its Western peers, Budel is being squeezed between a super-tight raw materials market and high energy costs.
Nyrstar successfully lobbied the Australian government for financial assistance to save its lead and zinc processing operations, and it is clearly hoping for something similar from the Dutch government.
Local power prices, according to Nyrstar, place Budel at a competitive disadvantage even relative to neighbouring countries.
A reprieve may be possible, but the underlying economics of zinc smelting continue to favour China.
It's ironic that just as the West has woken up to its dangerous dependency on China for critical minerals such as rare earths, it's becoming increasingly dependent on China for other, less glamorous metals such as zinc.
But LME short-position holders at least will be hoping China's zinc smelters keep shipping more metal to exchange warehouses.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Projects
Latest Multimedia
Latest News
Showroom
AxFlow AQS Liquid Transfer (Pty) Ltd is an Importer and Distributor of Pumps in Southern Africa
VISIT SHOWROOM
For over 60 years, VEGA has provided industry-leading products for the measurement of level, density, weight and pressure. As the inventor of the...
VISIT SHOWROOM
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation