How sums insured influence claim settlements
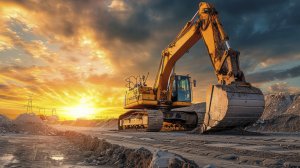


Plant and equipment represent a major part of any contractor's capital investment. It is therefore paramount to conclude insurance most suitable to the contractor's needs.
Understanding the different valuation bases of plant insurance
When arranging insurance for construction plant and equipment, many contractors focus on the sum insured. However, an equally important consideration is the basis on which the plant is insured. This can significantly influence how a claim is settled, particularly following a partial loss.
There are generally three ways in which construction plant and equipment can be insured:
- New Replacement Value
- Market Value
- Agreed Value
Principle of indemnity
Plant insurance is a policy of indemnity. Its purpose is to place the Insured, as far as reasonably possible, in the same financial position they occupied immediately before the loss occurred. This is subject to the terms, conditions and limits of the policy.
For this reason, the sum insured remains one of the most important factors in achieving an equitable claim settlement. Regardless of the valuation basis selected, inaccurate or outdated values may result in underinsurance and reduced claim payments.
In the event of a total loss, settlements under all three valuation bases will generally be determined by whichever is lower: the market value of the insured item immediately prior to the loss, or the sum insured. This is subject to values stated in the policy wording.
How the three valuation bases compare
New Replacement Value
Under New Replacement Value , the sum insured should represent the current new replacement value of the plant, which should be reviewed annually.
Where a partial loss occurs and repairs are required, new replacement parts, spares and components may be used without deductions for wear and tear, depreciation or betterment.
Market Value
Market Value remains one of the most used bases of valuation for construction plant.
Where a partial loss occurs, the Insurer may repair, replace, reinstate, or cash settle the loss, and suitable second-hand parts may be considered where appropriate. Betterment or a parts adjustment depreciation may apply in certain circumstances.
Agreed Value
Agreed Value is generally intended for specialised, purpose-built, or modified equipment for which reliable market values are not readily available.
Under this basis, the value of the equipment is agreed between the Insured and the Insurer before cover is placed, and this agreed value applies should a total loss occur. However, where equipment is readily replaceable and established market values exist, many Insurers will adjust settlement accordingly or will not offer an Agreed Value basis of valuation.
Why accurate plant valuations matter
Underinsurance triggers the Average condition, leaving the Insured to carry part of the loss. Overinsurance, conversely, brings no additional claims benefit. Since plant insurance remains a policy of indemnity, an Insurer will not pay more than the actual value of the loss, regardless of the sum insured. Plant should therefore be insured at an accurate, supportable value.
Specialised and modified plant
Particular attention should be given to custom-built, substantially modified, or engineered plant where establishing a market value may be more difficult.
In these circumstances, supporting information can assist Insurers in assessing an appropriate value before cover is placed. This includes professional valuation reports, original build costs, engineering drawings, and details of subsequent modifications. Establishing these values at inception can help reduce uncertainty should a claim arise.
Footnote on credit shortfall insurance
Equipment is often financed. In addition to the settlements discussed above, contractors should therefore also consider any credit shortfall insurance cover available through Consort.
Consort Technical Underwriting Managers
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Research Reports
Projects
Latest Multimedia
Latest News
Showroom
Complete range of security sealing solutions including security seals bags and labels.
VISIT SHOWROOM
SABAT Batteries is a renowned brand in the battery industry, manufacturing a wide range of batteries at its state-of-the-art production facility in...
VISIT SHOWROOM


Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation